Industry Guide
What Is an Introducing Broker?
An introducing broker (IB) is a firm or individual that solicits and accepts orders for futures, options on futures, retail forex, or swaps — but doesn't hold customer money. Instead, an IB “introduces” its customers to a futures commission merchant (FCM), which holds the funds, clears the trades, and carries the account.
A guide from the National Introducing Brokers Association · Updated October 2026
The short answer
- An IB registers with the CFTC and must be a member of NFA, the industry's self-regulatory organization.
- An IB never holds customer funds — those stay with the FCM, which must segregate futures and cleared-swaps customer funds from its own money. (Retail forex funds aren't segregated the same way.)
- An IB qualifies either independently, with its own capital, or under a guarantee agreement with an FCM.
- IBs work alongside related registrants — FCMs, CTAs, CPOs, and associated persons — all overseen by the same regulators.
How an introducing broker works
Think of the IB as the customer-facing half of a brokerage relationship. The IB finds and services clients — opening accounts, answering questions, and taking orders — while the FCM handles the money: holding margin deposits, executing and clearing trades, issuing statements, and carrying the account.
The arrangement lets independent brokers build their own practices without the capital and infrastructure it takes to run a clearing firm. IBs are typically compensated through commissions or a negotiated share of the fees their customers' trading generates, paid through the carrying FCM.
- Step 1
Customer
Opens an account and places orders through the introducing broker.
- Step 2
Introducing Broker
Solicits and services the account and accepts orders — but never holds the customer's money.
- Step 3
FCM
Holds customer funds (segregated, for futures and cleared swaps), executes and clears trades, and carries the account.
- Step 4
Exchange & Clearinghouse
Lists the contracts, matches buyers and sellers, and guarantees settlement of every trade.
Independent vs. guaranteed IBs
Every IB has to show regulators it can stand behind its obligations, and the rules allow two ways to do it. The choice shapes how the business operates — and it's why you'll see members of NIBA's broker directory listed as IIBs (independent) or GIBs (guaranteed).
| Independent IB (IIB) | Guaranteed IB (GIB) | |
|---|---|---|
| How it qualifies | Maintains its own adjusted net capital | Signs a guarantee agreement with an FCM (NFA Form 1-FR-IB Part B) |
| Minimum capital | $45,000 adjusted net capital under CFTC Regulation 1.17 — and NFA expects new applicants to show at least $50,000 | None — the guaranteeing FCM stands behind the IB |
| Financial reporting | Files periodic financial reports with NFA, including certified annual statements | Exempt from net capital and financial reporting requirements |
| Where business goes | Free to introduce customers to more than one FCM | Generally introduces all of its business to the guaranteeing FCM |
| Accountability | Answers for its own compliance | The guaranteeing FCM can also be disciplined for the IB's NFA rule violations |
| Typical fit | Established firms that want flexibility across clearing relationships | Newer or smaller firms that want a lighter regulatory footprint |
Who's who in the futures industry
The IB is one of several registration categories under the Commodity Exchange Act. Many firms hold more than one — and NIBA represents introducing brokers, CTAs, CPOs, and associated persons alike. About our membership.
Futures Commission Merchant
Accepts orders for futures, options, forex, or swaps and — unlike an IB — accepts money from customers to support them. FCMs must maintain at least $1,000,000 in adjusted net capital.
Introducing Broker
Solicits or accepts the same kinds of orders but does not accept money or other assets from customers. Independent or guaranteed, as described above.
Associated Person
An individual who solicits orders, customers, or customer funds — or supervises people who do — on behalf of an FCM, IB, CTA, CPO, or RFED. Generally must pass the Series 3 exam.
Commodity Trading Advisor
Advises others, for compensation or profit, on buying or selling futures, options, forex, or swaps — directly by managing accounts, or indirectly through newsletters, systems, or signals.
Commodity Pool Operator
Operates a commodity pool — a collective investment vehicle that combines participants' funds to trade derivatives — and solicits money for it.
Retail Foreign Exchange Dealer
Acts as the counterparty to off-exchange foreign currency transactions with retail customers. Note that retail forex funds are not segregated like futures funds, and NFA bars members from describing them as segregated or protected under the bankruptcy laws.
Swap Dealer
Holds itself out as a dealer in swaps, makes a market in swaps, or regularly enters into swaps as an ordinary course of business.
The regulators
CFTC
Commodity Futures Trading Commission
The federal agency that regulates the U.S. derivatives markets. Created by Congress in 1974 under the Commodity Futures Trading Commission Act, its mission is to “promote the integrity, resilience, and vibrancy of the U.S. derivatives markets through sound regulation.” The CFTC writes the rules — including the capital requirements above — and brings enforcement actions.
cftc.govNFA
National Futures Association
The industrywide self-regulatory organization for U.S. derivatives, designated by the CFTC in 1981 and operating since 1982. With few exceptions, CFTC-registered firms must be NFA members. NFA processes registrations, examines member firms, writes and enforces conduct rules, and offers arbitration for disputes.
nfa.futures.orgWhere futures meet securities
The SEC regulates the securities markets. Some firms are dual registrants — a securities broker-dealer that is also registered as an IB, for example — and answer to both regulators.Check before you trade
NFA's free BASIC lookup shows any firm's or individual's registration status, NFA membership, and regulatory history.
The exchanges
Futures and options trade on CFTC-registered exchanges known as designated contract markets, and every trade is backed by a clearinghouse that guarantees performance. The major U.S. venues:
CME Group
ChicagoThe world's leading derivatives marketplace, made up of four exchanges — CME, CBOT, NYMEX, and COMEX — covering equity indexes, interest rates, agriculture, energy, metals, and FX. Trades clear through CME Clearing.
Visit siteICE Futures U.S.
New YorkIntercontinental Exchange's U.S. futures market — home of the 'softs' (coffee, sugar, cocoa, cotton, and orange juice) and U.S. Dollar Index futures. ICE's global network also includes ICE Futures Europe, home of Brent crude.
Visit siteCboe Futures Exchange
ChicagoCboe's futures market (CFE), best known as the home of VIX futures — the benchmark way to trade expectations of U.S. stock-market volatility.
Visit siteMIAX Futures
MinneapolisFormerly the Minneapolis Grain Exchange (renamed in 2024), home of Minneapolis Hard Red Spring Wheat futures. Registered with the CFTC as both an exchange and a clearinghouse.
Visit siteBeyond the U.S.
Eurex
FrankfurtDeutsche Börse Group's derivatives exchange and Europe's leading derivatives market — home of EURO STOXX 50 index futures and German government bond (Bund) futures. Eurex is registered with the CFTC as a foreign board of trade, so U.S. customers can trade it directly, and its clearinghouse, Eurex Clearing, is a CFTC-registered derivatives clearing organization.
Of note for IBs: since September 2024, CFTC rule changes allow registered U.S. introducing brokers to become direct Eurex members.
Visit siteHow to become an introducing broker
Registration runs through NFA. The broad strokes:
- 1
Pass the Series 3
Each sole proprietor and associated person generally must pass the National Commodity Futures Examination (Series 3) within the two years before applying.
- 2
Choose independent or guaranteed
Either capitalize the firm and prepare financial statements, or arrange a guarantee agreement with the FCM that will carry your customers' accounts.
- 3
Register through NFA
File Form 7-R for the firm and Form 8-R (with fingerprints) for each principal and AP, and apply for NFA membership. Application fees are currently $200 for the firm and $85 per principal or AP.
- 4
Build your compliance program
Applicants provide anti-money-laundering procedures and a source-of-assets letter, and members maintain written supervisory procedures, an information security program, and a business continuity plan.
- 5
Stay current
Registration is ongoing: annual dues and registration updates, periodic financial filings for independent IBs, promotional-material rules, and NFA examinations.
NIBA University Outreach
Careers in futures
Thinking about working in the industry? This presentation from NIBA's university outreach series walks through how a futures trade moves from customer to IB to FCM to exchange — and the careers at every step, from brokerage and risk to compliance, technology, and trading.
Read the slide text
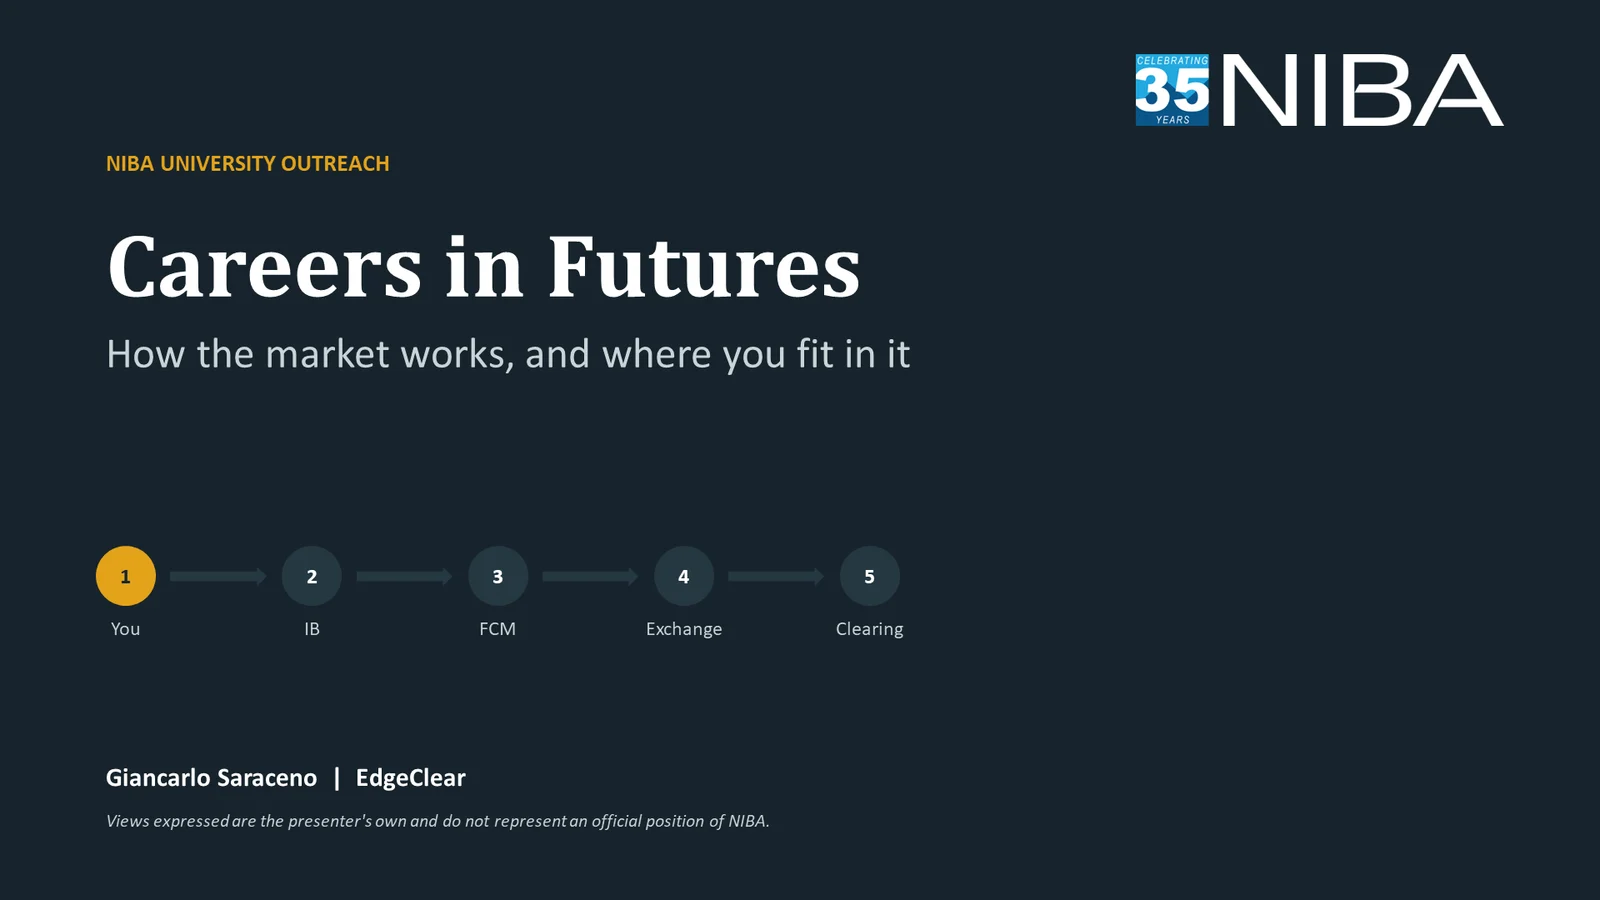
1. Careers in Futures
NIBA University Outreach — how the market works, and where you fit in it.
The chain: You → IB → FCM → Exchange → Clearing. Presented by Giancarlo Saraceno, EdgeClear.
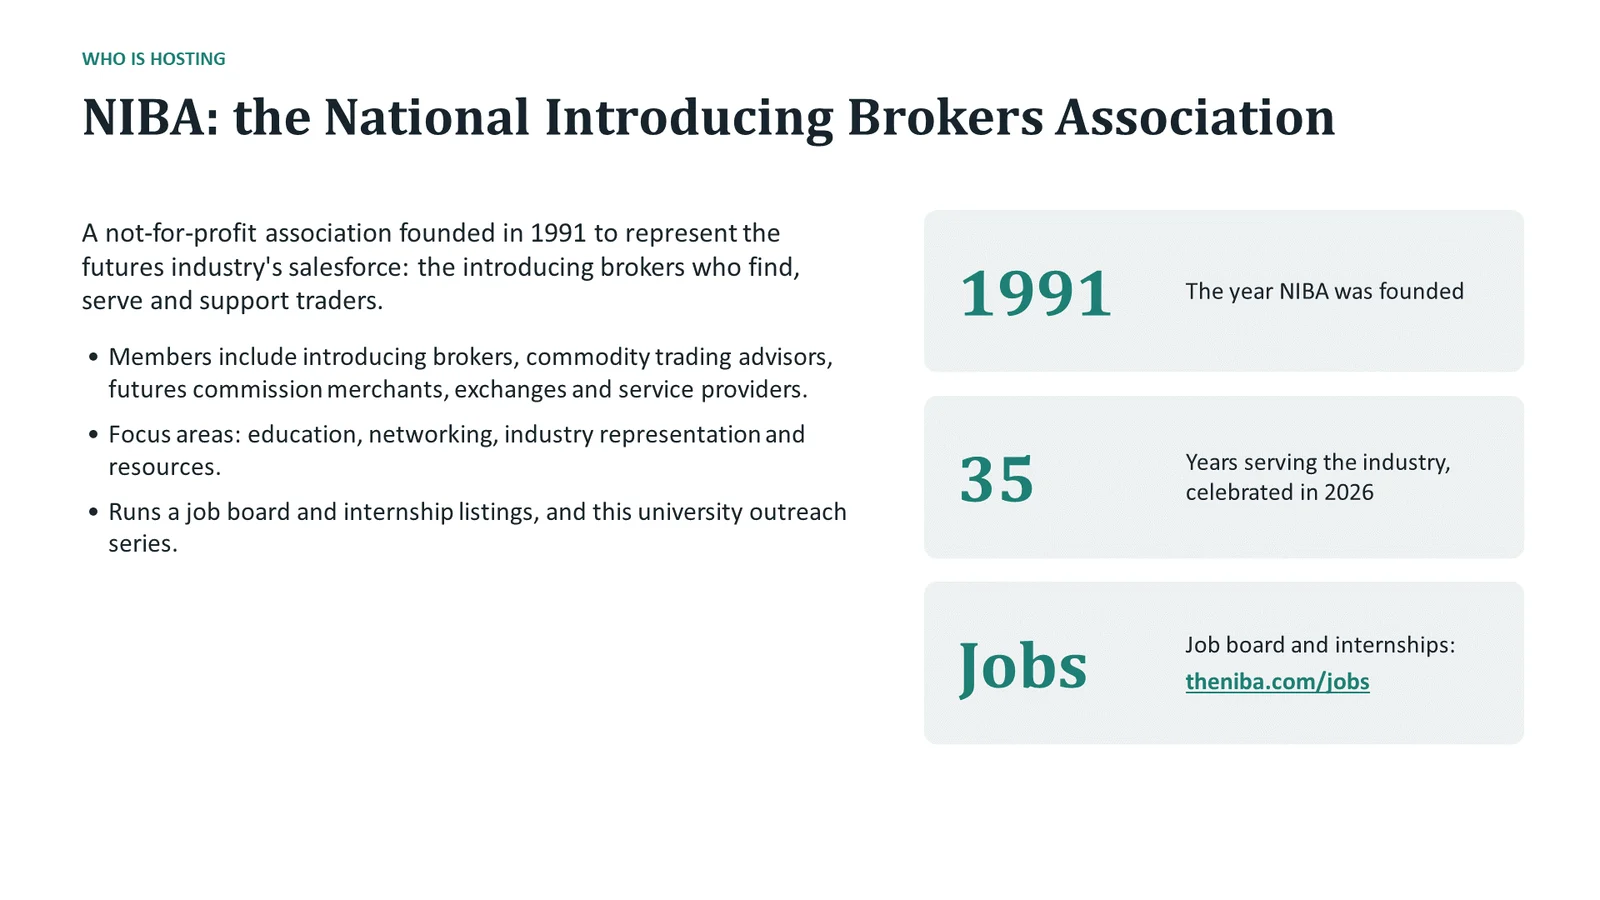
2. Who is hosting: NIBA
A not-for-profit association founded in 1991 to represent the futures industry's salesforce: the introducing brokers who find, serve and support traders.
Members include introducing brokers, commodity trading advisors, futures commission merchants, exchanges and service providers. Focus areas: education, networking, industry representation and resources.
NIBA runs a job board and internship listings (theniba.com/jobs) and this university outreach series.
3. What is a futures contract?
A standardized agreement to buy or sell something at a set price on a future date, traded on a regulated exchange.
Hedgers are businesses that want less risk — a farmer locking in a price for next fall's corn, an airline locking in jet fuel, a bank protecting against rate changes.
Speculators take on that risk for a potential profit and add liquidity, from individuals to large funds.
What trades: corn, crude oil, gold, the S&P 500, interest rates, currencies, even bitcoin.
4. Who does what
You, the customer: an individual, fund or business that wants to trade or hedge.
Introducing Broker: finds and services customers and accepts their orders; does not hold customer money.
Futures Commission Merchant: holds customer money, extends margin, manages risk and carries the accounts.
Exchange (DCM): where buyers and sellers meet — CME Group, Cboe Futures Exchange, ICE Futures U.S.
Clearinghouse (DCO): stands between every buyer and seller and guarantees the trade.
Regulators: the CFTC (federal regulator) and the NFA (the industry's self-regulatory organization).
5. Following a single trade
The order: the customer places it, the IB provides relationship and service, the FCM runs risk checks and routing, the exchange matches buyer and seller, and the clearinghouse guarantees the trade.
The money: the customer deposits funds directly with the FCM; the IB never touches customer money; the FCM keeps customer futures funds segregated and posts margin; the exchange publishes prices and sets the rules; the clearinghouse settles gains and losses every day.
Watching every step: the CFTC and the NFA. Not every FCM clears its own trades; many clear through a larger FCM that is a clearing member.
6. Introducing Broker vs. FCM
Main job — IB: find, educate and service customers and accept their orders. FCM: hold customer funds, extend margin, execute and carry accounts.
Customer money — IB: cannot accept or hold it. FCM: holds futures customer funds in segregated accounts.
Capital — IB: lower requirement, or guaranteed by an FCM. FCM: much higher requirement, reported to regulators regularly.
Oversight — both register with the CFTC and are NFA members; FCMs also follow exchange and clearing rules.
Typical jobs — IB: brokers, client services, marketing, business development. FCM: risk, operations, compliance, finance, technology, client services.
7. Careers beyond the trading desk
Brokerage & client relations (first seat: junior broker, Series 3) · Risk management (risk analyst) · Operations & clearing (operations associate) · Compliance & AML (compliance analyst).
Technology (junior developer) · Finance & regulatory reporting (regulatory accountant) · Marketing & business development (marketing coordinator) · Legal & regulation (paralegal, examiner).
8. Every box in the chain is an employer
IBs hire brokers (associated persons), client services, marketing and business development. FCMs hire risk, operations and clearing, compliance and AML, finance and regulatory reporting, and technology.
Exchanges hire product development, market surveillance, sales and technology. Clearinghouses hire clearing risk, collateral management, default management and operations. Regulators hire examiners, investigators, policy analysts and attorneys.
Plus the wider ecosystem: trading platforms, market data, software and research firms.
9. And yes, trading
Trader (proprietary firm, bank, fund or a commercial hedger's desk), CTA (gives futures trading advice or manages accounts; registered with the CFTC), and quant/research (builds and tests models).
Reality check: trading is the most visible and most competitive seat. Many successful traders started in risk, operations or brokerage. Futures trading involves substantial risk of loss and is not suitable for everyone.
10. How to get started
1. Learn the plumbing — take free courses from exchanges such as CME Group and read industry news daily. 2. Get licensed — the Series 3 is the core futures license exam the NFA requires for brokers; many firms sponsor it.
3. Get in the room — come to NIBA events and check theniba.com/jobs. 4. Take the first seat — operations, risk and compliance roles are common and valuable entry points.
Skills every firm asks for: Excel, SQL or Python, clear writing, attention to detail, curiosity about markets.
11. Questions?
The market needs far more than traders. Find the seat that fits you. Jobs and internships: theniba.com/jobs.
Views expressed are the presenter's own and do not represent an official position of NIBA.
Presented by Giancarlo Saraceno, EdgeClear. Views expressed are the presenter's own and do not represent an official position of NIBA. Looking for a role? Browse the NIBA job board.
Further reading from the NIBA Journal
Special Alert: Introducing Brokers will be featured at FIA EXPO 2025
October 2025
CFTC Grants Certain AML Relief to IBs that do not introduce customers to FCMs
July 2019
Marketing and Promotional Material | Compliance Reminders from NFA
June 2023
NFA ISSP Amendments
March 2019
CFTC Further Narrows Regulation 4.7 Exemption for CTAs and CPOs
November 2024
NFA Launches Redesigned BASIC Tool
September 2019
Frequently asked questions
Does an introducing broker hold my money?
No. By definition, an introducing broker does not accept money or other assets from customers. Your funds are held by the futures commission merchant (FCM) that carries your account. For futures and cleared swaps, the FCM must keep customer funds segregated from its own money. Retail forex is different: forex funds are not segregated in the same way and do not receive special protection under the bankruptcy laws.
What is the difference between an introducing broker and an FCM?
Both can solicit and accept orders, but only an FCM accepts customer funds. The IB handles the customer relationship — opening accounts, service, and order-taking — while the FCM holds the money, clears the trades, and carries the account.
Is a guaranteed IB less safe than an independent IB?
Not inherently. The two structures meet the same regulatory obligation in different ways: an independent IB maintains its own capital, while a guaranteed IB is backed by an FCM that is accountable for it. In both cases, customer funds are held at the FCM, not the IB.
How can I check whether an introducing broker is registered?
Use NFA's free BASIC (Background Affiliation Status Information Center) lookup at nfa.futures.org. It shows a firm's or individual's registration status, NFA membership, and any regulatory or disciplinary history.
Can an introducing broker also be a CTA?
Yes. Many firms and individuals hold more than one registration — an IB that also advises on or manages trading accounts, for example, may also register as a commodity trading advisor.
How do introducing brokers get paid?
IBs are typically compensated through commissions or a negotiated share of the fees generated by their customers' trading, paid through the FCM that carries the accounts.
Looking for an introducing broker?
Search NIBA's directory of futures brokers and CTAs by state, or browse the FCMs, exchanges, and service providers that support them.
This guide is educational and isn't legal or regulatory advice. Requirements and fees change — confirm current rules with NFA and the CFTC before acting on them.
Sources
- NFA — Who has to register
- NFA — Introducing broker registration
- NFA — Guaranteed IB requirements
- NFA — IB applicant compliance requirements
- NFA — Proficiency requirements
- NFA — Forex regulatory guide
- CFTC — FCM and IB minimum net capital requirements
- CFTC — About the Commission
- CFTC — Orders of registration to foreign boards of trade, incl. Eurex (2016)
- Eurex — Direct membership for U.S. introducing brokers (2024)